
The steps in brief: Under the RBI direction the date of your request matters, because the 7 working day clock starts from there once dues are cleared.
How to close a credit card in India: step by step
Step 1: Decide whether to close or downgrade
If the issue is the annual fee, first try to get it waived or move to a no-fee variant. Our guide to annual fee waiver explains how, and our credit card charges comparison lists fees and interest for ten issuers where a dated source was available. Closing an old card can shorten your credit history, so keep the oldest, lowest-cost card if you can.
Step 2: Clear every outstanding amount
Pay the full statement balance, any unbilled transactions that are still pending, EMIs, and any fees or interest. If you have an EMI conversion running, read our credit card EMI guide because pre-closure of an EMI can attract a fee. Check your billing cycle so that the last statement settles completely, and remove the card from every merchant app and subscription.
Step 3: Redeem reward points and cancel auto-debits
Points and cashback usually lapse on closure. Redeem them first. Cancel any standing instruction, such as an auto-debit that pays the card bill, only after the last bill is cleared.
Step 4: Send the closure request in writing
Use the issuer’s customer-care email, app or branch, and ask for a service request number. Keep screenshots or the email. Under the RBI direction the date of your request matters, because the 7 working day clock starts from there once dues are cleared.
Step 5: Get the no-dues certificate and confirm the card is closed
Ask for a closure confirmation and a no-dues certificate. Destroy the physical card by cutting it through the chip and magnetic strip. Read how fraud protection works if you spot any transaction after closure.
Step 6: Check your credit report after 30 days
Pull your credit report about 30 days later and confirm the card shows as closed with a zero balance. If the status is wrong, raise a dispute with the credit bureau and the issuer. Our credit score guide explains how to read the report.
RBI rules for credit card closure
| Rule | What the RBI direction says | Source and date |
|---|---|---|
| Closure timeline | Card must be closed within 7 working days of the request once dues are cleared | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Penalty for delay | Rs 500 per day of delay, payable by the issuer to the customer | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Points and rewards | Customer can redeem points before closure | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Proof of closure | Customer should receive confirmation and a no-dues certificate | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Credit report | Issuer must update the bureau; customer should verify after about 30 days | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Unused cards | A card unused for over one year can be closed after notice, with 30 days given to the customer to respond | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
| Complaints | Escalate to the issuer’s nodal officer, then the RBI Integrated Ombudsman | RBI Master Direction on Credit Card and Debit Card 2022, as reported by CardTrail on 19 Mar 2026, accessed 7 Oct 2026 |
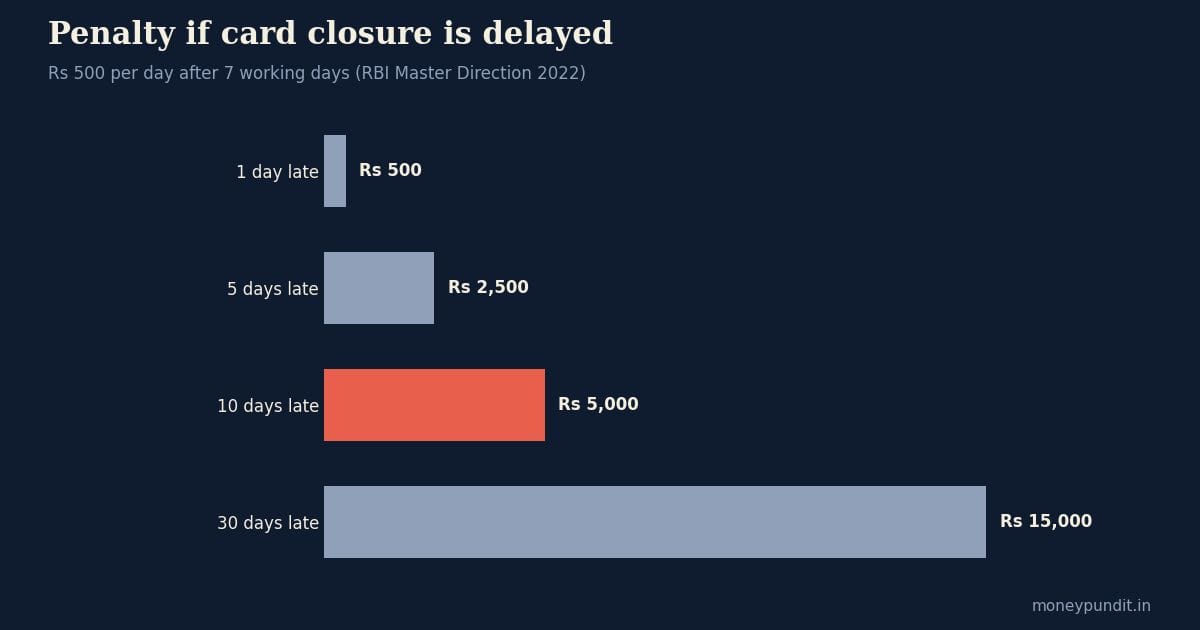
Penalty for delayed credit card closure
| Delay beyond 7 working days | Penalty owed to you at Rs 500 per day |
|---|---|
| 1 day | Rs 500 |
| 5 days | Rs 2,500 |
| 10 days | Rs 5,000 |
| 30 days | Rs 15,000 |
These totals are our own arithmetic on the Rs 500 per day rule above. In practice, you should send a written reminder and cite the RBI direction if the issuer is late. The penalty is not automatic in every case, so keep the dates and ask the issuer in writing.
Does closing a credit card hurt your credit score?
It can, for two reasons. First, your total credit limit drops, so the share of the limit you use goes up, and a high utilisation ratio can pull the score down. Second, if the card is your oldest, the average age of your accounts can shrink. Neither effect is permanent, and a clean repayment record on your other accounts helps the score recover. If you carry a balance, look at balance transfer options before you close the card. If you are comparing cards to keep, see best credit cards in India and credit card vs debit card.
Issuer-specific closure processes: what we could and could not verify
| Issuer group | Verified closure process or charge | Status |
|---|---|---|
| HDFC Bank, SBI Card, ICICI Bank, Axis Bank, Kotak Mahindra Bank | No dated issuer source reviewed for closure steps or charges | Not verified, use the RBI timeline and ask for a service request number |
| PSB-issued cards (PNB, Bank of Baroda, Canara, Union) | No dated issuer source reviewed | Not verified |
| Standard Chartered, HSBC, AU, Federal, IDFC FIRST, RBL | No dated issuer source reviewed | Not verified |
Every issuer must follow the RBI direction, so the 7 working day rule and the Rs 500 per day penalty apply across all of them. What varies is the channel (app, email, phone or branch) and whether a retention team calls you. We left per-issuer steps unverified rather than copy aggregator summaries that disagree with each other.
What if the issuer refuses or delays?
Write to the issuer and cite the RBI Master Direction. If the issuer does not respond, go to its nodal officer and then file a complaint on the RBI Integrated Ombudsman. The Reserve Bank of India publishes the directions in full. Keep every date, because the ombudsman looks at when you applied and when the dues were cleared.
Common mistakes
- Closing with unbilled spends or a running EMI, so the card stays open or a new bill arrives.
- Forgetting to redeem points.
- Not asking for a no-dues certificate.
- Closing your oldest card first when a newer card has the annual fee.
Closing checklist
- Try a fee waiver or downgrade first.
- Clear all dues, EMIs and unbilled spends.
- Redeem points and remove the card from apps.
- Send a written closure request and note the date.
- Collect the no-dues certificate.
- Check the credit report after 30 days.
Frequently asked questions
How long does it take to close a credit card in India?
The RBI direction requires closure within 7 working days of your request, provided dues are cleared. The issuer owes you Rs 500 per day if it is late.
Is there a fee to close a credit card?
The RBI direction does not set a closure fee, but outstanding annual fees, interest and EMI pre-closure charges still apply. We found no dated issuer source for a closure fee, so ask in writing.
Will closing a credit card reduce my credit score?
It can, because your total limit falls and the average age of your accounts can drop. The effect usually eases if you repay other accounts on time.
What happens to my reward points when I close a credit card?
Points are typically forfeited on closure, so redeem them first. The RBI direction lets you redeem points before closing.
Can the bank close my credit card without telling me?
For a card unused for over one year, the issuer can close it after notice and a 30 day window for you to respond, as per the RBI direction reported by CardTrail on 19 Mar 2026.
Where do I complain if my credit card is not closed on time?
Start with the issuer, then its nodal officer, then the RBI Integrated Ombudsman.
Information only, not financial advice. Rules and issuer practice change; verify with your issuer. Last reviewed 7 Oct 2026.