
Home insurance in india in brief: Home insurance is one of the most neglected insurance categories in India, with fewer than 1% of homes insured.
Home insurance is one of the most neglected insurance categories in India, with fewer than 1% of homes insured. Yet your home is likely your largest financial asset, and a single event, fire, earthquake, flood, or burglary, can cause devastating financial loss. Understanding home insurance options helps protect your most valuable investment.
Home Insurance In India: What Home Insurance Covers
A standard home insurance policy covers structural damage to your building from fire, lightning, explosion, storms, floods, earthquakes, and riots. Contents insurance covers household items like furniture, electronics, appliances, jewelry, and clothing against the same perils plus burglary and theft. All-risk policies extend coverage to accidental damage. Some comprehensive policies also cover temporary accommodation costs if your home becomes uninhabitable during repairs.
Types of Home Insurance Policies
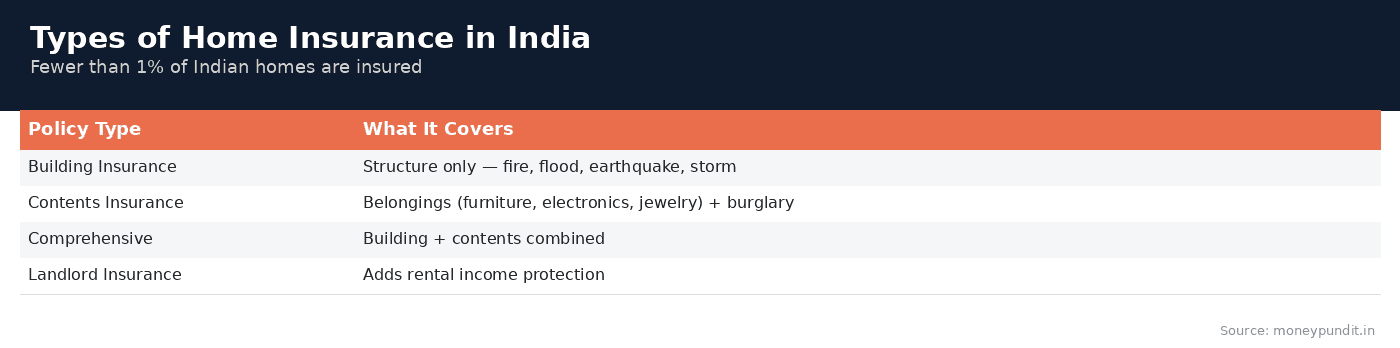
Building insurance covers the structure of your home and is essential for homeowners. It is usually mandatory for home loan borrowers but should be maintained even after the loan is paid off. Contents insurance covers your belongings inside the home and is relevant for both owners and tenants. Comprehensive policies combine building and contents coverage. Landlord insurance adds rental income protection if your property becomes unrentable due to insured damage.
How to Calculate Coverage Amount
For building insurance, calculate the reconstruction cost (not market value or property purchase price) using the carpet area multiplied by the current construction cost per square foot in your city. For a 1,500 sq ft apartment in Mumbai at ₹3,500/sq ft reconstruction cost, the building cover should be approximately ₹52.5 lakh. For contents, list all valuable items with replacement values. Most people underestimate their contents value, a typical 3BHK apartment has ₹10-25 lakh worth of contents.
Top Home Insurance Providers
HDFC ERGO Home Insurance offers comprehensive building plus contents coverage with add-ons for electronic equipment and valuable items. ICICI Lombard Home Protect covers building structure, contents, and offers temporary accommodation benefit. SBI General Home Insurance is affordable with flexible coverage options. Bajaj Allianz Home Insurance provides coverage against 12+ perils including terrorism. Compare quotes based on coverage scope, exclusions, and claim settlement track record rather than just premium.
Is home insurance mandatory?
Home insurance is not legally mandatory for homeowners but is typically required by banks for home loan borrowers. However, given the financial impact of property damage, it is strongly recommended for all homeowners regardless of loan status.
Does home insurance cover natural disasters?
Standard policies cover most natural disasters including fire, storm, flood, and earthquake. However, some policies may list earthquake as an optional add-on. Always verify that your policy covers the natural disaster risks specific to your area.
Why Home Insurance Is Essential
For most Indian families, their home is their single largest asset, often worth ₹30 lakh to ₹3 crore or more. Yet home insurance penetration in India remains below 1%, compared to over 90% in developed countries. A comprehensive home insurance policy protects against fire, natural disasters (earthquakes, floods, cyclones), theft and burglary, electrical damage, water damage from plumbing failures, and even terrorism, risks that can cause losses running into lakhs.
Home insurance in India comes in two main types: structure insurance (covers the building itself, walls, roof, flooring, fixtures) and contents insurance (covers belongings inside, furniture, electronics, jewellery, appliances). Most policies offer both as a bundled package. The annual premium is surprisingly affordable, typically ₹2,000-₹8,000 for a ₹50 lakh structure cover with ₹10 lakh contents cover, making it one of the most cost-effective insurance products available.
What Home Insurance Covers (and Doesn’t)
Standard home insurance policies cover damage from fire, lightning, explosions, storms, floods, earthquakes, riots, aircraft damage, and impact from vehicles or falling trees. Add-on covers extend protection to electronic equipment breakdown, jewellery and valuables (with separate valuation), alternative accommodation costs if your home becomes uninhabitable, and rent loss if you’re a landlord.
Common exclusions include damage from war, nuclear risks, intentional damage, normal wear and tear, pre-existing defects, and damage from pets. Most policies also exclude damage to the land itself, construction-phase risks (which need a separate contractor’s all-risk policy), and losses from governmental action. Read the policy wording carefully, and consider endorsements or add-ons for risks specific to your location, earthquake cover in seismic zones, flood cover in low-lying areas, or cyclone cover in coastal regions.
How to Choose the Right Policy
When selecting home insurance, ensure the sum insured reflects the actual reconstruction cost of your home, not the market value (which includes land). Get a professional valuation for accurate coverage. For contents, create a room-by-room inventory with purchase receipts or photos as proof of ownership, this dramatically speeds up claims processing.
Compare policies from HDFC Ergo, ICICI Lombard, Bajaj Allianz, Tata AIG, and New India Assurance on coverage scope, claim settlement ratio, and premium. Opt for reinstatement value (replacement cost) over indemnity value (depreciated cost). Paying slightly more ensures you receive the full replacement cost without depreciation deductions during claims. If you have a home loan, note that your lender’s mandatory fire insurance covers only their loan exposure, not your full property value or contents. Supplement it with a comprehensive home insurance policy for complete protection.
References: Sebi.gov.in
Source: sebi.gov.in
Home insurance in india: Key Takeaways
Key points on home insurance in india:
- A standard home insurance policy covers structural damage to your building from fire, lightning, explosion, storms, floods, earthquakes, and riots.
- Building insurance covers the structure of your home and is essential for homeowners.
- For building insurance, calculate the reconstruction cost (not market value or property purchase price) using the carpet area multiplied by the current construction cost per square foot in your city.
Verify the latest home insurance in india figures with IRDAI before you act.
Using home insurance in india in Your Plan
Putting home insurance in india into practice starts with your own numbers. Run them through our SIP calculator and tax calculator to see how home insurance in india fits your goals, then compare options in our FD rates guide. Whatever you decide about home insurance in india, review it every year and keep records.
In short, home insurance in india works best when matched to your time horizon, your tax bracket and your risk comfort. Revisit home insurance in india whenever rules or rates change.