
Looking for the best FD rates India 2026? Fixed deposits remain one of India’s most trusted investment options, offering guaranteed returns with zero market risk. With the RBI raising the repo rate to 5.50% in October 2026, FD interest rates are stabilising at attractive levels, especially from small finance banks and select NBFCs that offer significantly higher rates than traditional large banks. This comprehensive guide compares the best FD rates India 2026 across SBI, HDFC, ICICI, small finance banks, Post Office, and NBFCs to help you find the highest fixed deposit returns for your investment.
Borrowing instead? Compare home loan interest rates 2026.
Living abroad? See NRE FD rates 2026 for NRI deposit rates.
Prefer government-backed deposits? Compare post office vs bank FD rates before you choose.
Senior citizen? See the senior citizen FD rates for October 2026, with small finance bank rates up to 8.5%.
RBI policy update (7 October 2026): the RBI raised the repo rate by 25 bps to 5.50%. Banks usually reprice deposits a few weeks later, and the rates below are as of early October, before the decision. Read our RBI repo rate hike guide for FDs and EMIs.
Best FD Rates India 2026: Top Bank Interest Rates Compared
Compare the best FD rates India 2026 bank by bank. The tables below cover all 12 public sector banks, 23 private banks, 10 small finance banks and 3 foreign banks. Rates are as of 1 October 2026, before the RBI raised the repo rate to 5.50% on 7 October, so expect many banks to revise upward over the coming weeks. Senior citizens usually get an extra 0.25% to 0.75%; see the senior citizen FD rates table for all 45 banks.
Public sector bank FD rates (all 12 banks)
| Bank | Highest slab (%) | 1 year (%) | 3 years (%) | 5 years (%) |
|---|---|---|---|---|
| State Bank of India | 6.45 | 6.25 | 6.30 | 6.05 |
| Punjab National Bank | 6.60 | 6.25 | 6.35 | 6.10 |
| Bank of Baroda | 6.75 | 6.25 | 6.25 | 6.30 |
| Canara Bank | 6.60 | 6.25 | 6.25 | 6.25 |
| Union Bank of India | 6.55 | 6.20 | 6.10 | 6.00 |
| Bank of India | 6.85 | 6.50 | 6.70 | 6.00 |
| Indian Bank | 6.65 | 6.10 | 6.05 | 6.00 |
| Central Bank of India | 6.75 | 6.10 | 6.00 | 6.00 |
| Indian Overseas Bank | 6.60 | 6.50 | 6.10 | 6.10 |
| UCO Bank | 6.45 | 6.10 | 6.00 | 6.00 |
| Bank of Maharashtra | 6.65 | 6.20 | 5.25 | 5.00 |
| Punjab & Sind Bank | 6.85 | 5.85 | 5.85 | 5.95 |
Source: Paisabazaar FD rate tables, rates as of 1 October 2026, general citizens, deposits below Rs 3 crore. Always confirm on the bank’s own website before booking.
Private sector bank FD rates
| Bank | Highest slab (%) | 1 year (%) | 3 years (%) | 5 years (%) |
|---|---|---|---|---|
| HDFC Bank | 6.50 | 6.25 | 6.45 | 6.40 |
| ICICI Bank | 6.50 | 6.25 | 6.45 | 6.50 |
| Axis Bank | 6.50 | 6.25 | 6.50 | 6.50 |
| Kotak Mahindra Bank | 6.65 | 6.50 | 6.40 | 6.25 |
| IndusInd Bank | 7.00 | 6.75 | 7.00 | 6.65 |
| Yes Bank | 7.25 | 6.65 | 7.00 | 6.75 |
| IDFC FIRST Bank | 7.10 | 6.50 | 7.10 | 6.75 |
| IDBI Bank | 6.55 | 6.20 | 6.35 | 6.25 |
| Federal Bank | 6.70 | 6.25 | 6.50 | 6.40 |
| Bandhan Bank | 7.45 | 7.00 | 7.25 | 5.85 |
| RBL Bank | 7.20 | 7.00 | 7.20 | 6.70 |
| DCB Bank | 7.50 | 6.90 | 7.00 | 7.50 |
| SBM Bank India | 7.65 | 7.10 | 7.10 | 7.00 |
| CSB Bank | 7.10 | 5.00 | 5.75 | 5.75 |
| City Union Bank | 7.25 | 6.65 | 6.50 | 6.55 |
| Dhanlaxmi Bank | 7.25 | 6.25 | 6.50 | 6.50 |
| Jammu & Kashmir Bank | 7.05 | 6.55 | 6.70 | 6.75 |
| Karnataka Bank | 7.00 | 6.50 | 6.15 | 6.15 |
| Karur Vysya Bank | 6.70 | 6.25 | 6.40 | 6.25 |
| Nainital Bank | 6.60 | 6.40 | 6.25 | 5.75 |
| South Indian Bank | 6.80 | 6.35 | 6.20 | 5.70 |
| Tamilnad Mercantile Bank | 7.25 | 6.80 | 6.70 | 6.70 |
| DBS Bank India | 6.85 | 6.30 | 6.40 | 6.25 |
Source: Paisabazaar FD rate tables, rates as of 1 October 2026, general citizens, deposits below Rs 3 crore. Always confirm on the bank’s own website before booking.
Small finance bank FD rates
| Bank | Highest slab (%) | 1 year (%) | 3 years (%) | 5 years (%) |
|---|---|---|---|---|
| Suryoday Small Finance Bank | 8.25 | 7.25 | 7.25 | 8.25 |
| Utkarsh Small Finance Bank | 8.10 | 6.00 | 7.50 | 7.00 |
| Jana Small Finance Bank | 8.00 | 7.00 | 8.00 | 7.77 |
| ESAF Small Finance Bank | 8.00 | 6.00 | 6.00 | 5.75 |
| Shivalik Small Finance Bank | 8.00 | 6.00 | 7.50 | 6.25 |
| Equitas Small Finance Bank | 8.00 | 7.10 | 7.10 | 7.00 |
| Ujjivan Small Finance Bank | 7.80 | 7.25 | 7.25 | 7.20 |
| Unity Small Finance Bank | 7.50 | 7.50 | 6.75 | 6.75 |
| AU Small Finance Bank | 7.40 | 6.35 | 7.40 | 6.75 |
| Capital Small Finance Bank | 7.15 | 7.00 | 7.00 | 6.90 |
Source: Paisabazaar FD rate tables, rates as of 1 October 2026, general citizens, deposits below Rs 3 crore. Always confirm on the bank’s own website before booking.
Foreign bank FD rates in India
| Bank | Highest slab (%) | 1 year (%) | 3 years (%) | 5 years (%) |
|---|---|---|---|---|
| Deutsche Bank | 7.00 | 5.00 | 6.25 | 6.25 |
| HSBC India | 5.50 | 4.00 | 5.35 | 5.50 |
| Standard Chartered Bank | 6.60 | 6.60 | 6.50 | 6.25 |
Source: Paisabazaar FD rate tables, rates as of 1 October 2026, general citizens, deposits below Rs 3 crore. Always confirm on the bank’s own website before booking.
Highest slab means the best rate a bank advertises for any tenure, so it can sit on a short or odd tenure such as 444 days. Small finance banks pay the highest rates, but deposits up to Rs 5 lakh per depositor per bank are insured by DICGC, the same as at every other bank. Compare payouts with the FD calculator and track past moves in the FD interest rate history.
Among large banks the sweet spot is usually the 1 to 2 year bracket, and rates often dip for 3 to 5 years, as the tables show. Use our FD Calculator to compute the maturity amount for your deposit and tenure. Prefer monthly saving? Compare RD interest rates across 27 banks.
Small Finance Banks: Where the Best FD Rates India 2026 Are
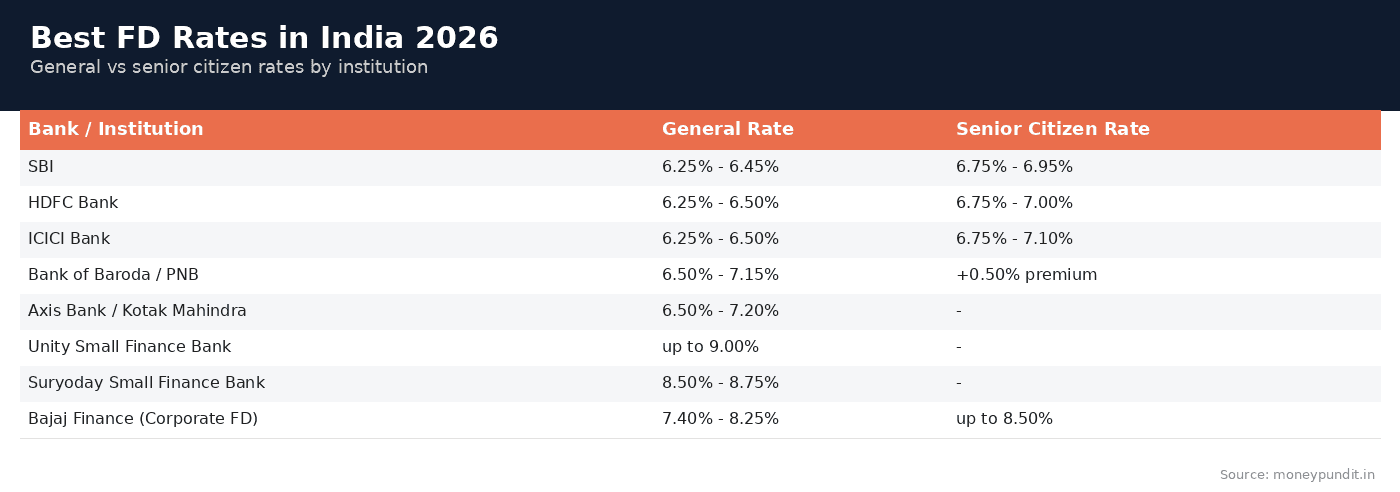
Small finance banks consistently outperform large banks by 0.75-1.50% across all tenures. Unity Small Finance Bank leads with rates up to 9.00% for specific tenures, followed by Suryoday Small Finance Bank at 8.50-8.75%, Utkarsh Small Finance Bank at 8.25-8.50%, and Northeast Small Finance Bank at 8.00-8.50%. AU Small Finance Bank and Equitas Small Finance Bank offer 7.75-8.25%, still significantly above large bank rates.
The critical question: are small finance bank FDs safe? Yes: deposits up to ₹5 lakh per depositor per bank are fully insured by DICGC (Deposit Insurance and Credit Guarantee Corporation), exactly the same protection as SBI or HDFC Bank FDs. For amounts above ₹5 lakh, spread deposits across multiple small finance banks to stay within the insurance limit at each. This strategy lets you earn 1-1.5% more than large banks while maintaining complete safety on your entire deposit.
Corporate FDs and NBFC Fixed Deposits
Corporate FDs from highly-rated NBFCs offer another avenue for higher returns. Bajaj Finance FD (rated CRISIL AAA/STABLE) offers 7.40-8.25% for general customers and up to 8.50% for senior citizens, among the highest in the AAA-rated category. Mahindra Finance (rated CRISIL AA+) offers 7.50-8.10%, and Shriram Finance provides 7.60-8.40% across various tenures.
Important distinction: corporate FDs are not insured by DICGC, so the issuing company’s credit rating matters enormously. Stick to AAA or AA+ rated companies only, lower-rated corporate FDs carry meaningful default risk despite offering tempting rates. Check the company’s latest credit rating on CRISIL, ICRA, or CARE websites before investing. Corporate FDs also lack premature withdrawal flexibility that bank FDs offer, most charge a 1-2% penalty or don’t allow premature withdrawal at all.
Tax-Saving Fixed Deposits Under Section 80C
Tax-saving FDs with a 5-year lock-in qualify for deductions under Section 80C up to ₹1.5 lakh per financial year. Most banks offer 6.50-7.50% on 5-year tax-saving FDs, with senior citizens getting 7.00-8.00%. While the rates are decent, remember that FD interest is fully taxable at your income slab rate, effectively reducing your return significantly.
For someone in the 30% tax bracket, a 7.5% FD yields only 5.25% post-tax, below the inflation rate in many years. Compare this with ELSS mutual funds that also qualify for Section 80C but have delivered 12-15% historical returns with a shorter 3-year lock-in. Tax-saving FDs make sense primarily for very conservative investors who cannot stomach any market volatility, or as a portion of a diversified Section 80C portfolio.
FD Laddering Strategy for Maximum Returns
Instead of locking your entire corpus in one FD, use a laddering strategy: divide your investment across multiple FDs with staggered maturities. For example, with ₹10 lakh, invest ₹2.5 lakh each in 1-year, 2-year, 3-year, and 5-year FDs. As each shorter FD matures, reinvest at the prevailing best rate for a 5-year term. After the initial cycle, you’ll have a 5-year FD maturing every year, providing annual liquidity while earning long-term rates.
This approach hedges against interest rate fluctuations: if rates rise, your maturing shorter FDs get reinvested at higher rates; if rates fall, your existing longer FDs continue earning the previously locked-in higher rates. Laddering also provides planned liquidity without premature withdrawal penalties. Combine bank FD laddering with small finance bank and NBFC FDs for a diversified fixed-income portfolio that maximizes returns within your risk tolerance.
How to Choose the Best FD Rates India 2026 for Your Needs
For emergency funds (1-3 months), choose sweep-in or flexi-FDs at your salary bank for instant liquidity. For short-term goals (1-2 years), compare rates across small finance banks for the best yields with DICGC protection. For medium-term goals (3-5 years), consider a mix of bank FDs and AAA-rated corporate FDs. For retirement income, non-cumulative FDs with monthly/quarterly interest payout from banks with the highest senior citizen rates provide regular cash flow.
Always compare the effective yield after accounting for tax. A 7.5% FD in the 30% bracket gives you only 5.25%, potentially less than a PPF at 7.1% (which is fully tax-free). For long-term wealth building, FDs should complement, not replace, equity investments. Check RBI Bonds vs FD for another fixed-income alternative with different tax treatment. Senior citizens should explore the Senior Citizens Savings Scheme (SCSS) at 8.2% with quarterly payouts and Section 80C eligibility, often the best fixed-income option for retirees.
Best FD Rates India 2026 vs Other Investment Options
When comparing the best FD rates India 2026 with other investment options, fixed deposits offer a unique combination of safety and predictable returns. While equity mutual funds have delivered 12-15% annualized returns over the long term, they come with significant market risk. Debt mutual funds offer 6-8% returns with moderate risk, while PPF provides 7.1% with a 15-year lock-in period.
For conservative investors seeking the best FD rates India 2026, small finance banks offering 8.5-9.25% represent an excellent risk-reward balance, your deposits up to Rs 5 lakh are fully insured by DICGC, making them as safe as any nationalized bank FD. Corporate FDs from AAA-rated companies like HDFC Ltd and Bajaj Finance offer 7.5-8.35%, providing a middle ground between bank FDs and equity investments.
The ideal strategy is to diversify across FD tenures and institutions. Use our FD Calculator to compare maturity amounts across different banks and tenures, and consider a debt mutual fund allocation for tax-efficient returns above 5 lakh investment amounts.
Related Financial Tools and Guides
Make the most of your fixed deposit investments with these resources from MoneyPundit:
- FD Calculator: Calculate your maturity amount and interest earned for any bank and tenure
- PPF vs FD vs ELSS Comparison: Which tax-saving investment gives the best returns in 2026?
- Best Savings Account Interest Rates 2026: Compare savings rates alongside your FD portfolio
- NPS Calculator: Plan your retirement corpus alongside your FD investments
- Power of Compounding: Understand how compound interest works in FDs and other investments
For official FD rate updates, always verify with the Reserve Bank of India (RBI) website and individual bank portals like SBI, HDFC Bank, and ICICI Bank. You can also check the India Post website for Post Office FD rates and the DICGC portal for deposit insurance details.
Frequently Asked Questions About Best FD Rates India 2026
Are small finance bank FDs safe?
Yes, deposits up to ₹5 lakh per depositor per bank are insured by DICGC, the same protection available at large banks like SBI. For larger amounts, spread across multiple banks.
What are the best FD rates India 2026 and which bank gives the highest?
Unity Small Finance Bank offers up to 9.00% for specific tenures. Among large banks, the highest general customer rates are around 6.50%. Corporate FDs from top-rated NBFCs offer up to 8.50%.
Should I choose cumulative or non-cumulative FD?
Cumulative FDs (interest reinvested and paid at maturity) are better for wealth building as the interest compounds. Non-cumulative FDs (regular interest payouts) suit retirees or those needing periodic income. Cumulative FDs always yield a higher total return due to compounding.
Is it better to invest in FD or mutual funds?
FDs offer guaranteed, risk-free returns ideal for conservative investors and short-term goals. Mutual funds (especially equity) offer higher potential returns (12-15% historically) but with market risk, better for long-term goals (7+ years). A balanced portfolio typically includes both, allocated based on your risk tolerance and time horizon.
Related reading: SBI FD Calculator · FD Interest Rate History (2019-2026) · RBI Floating Rate Bonds vs FD